By Clement Nwoji, Abuja
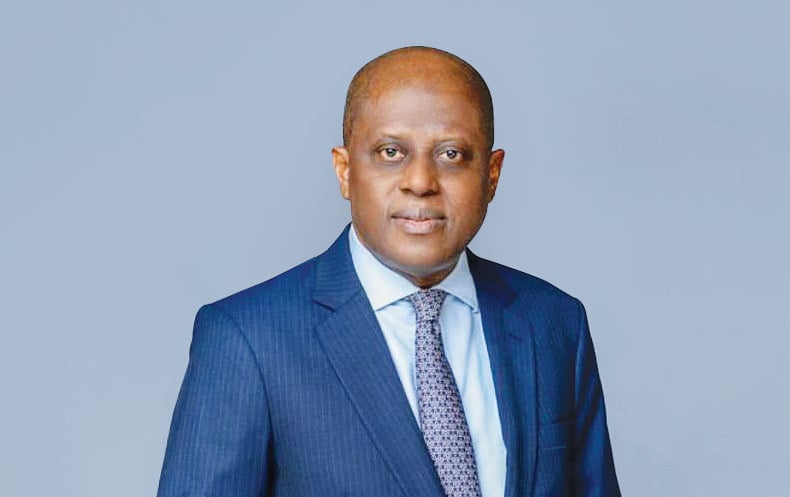
Having clocked 36 months at the helm of affairs of the Central Bank of Nigeria (CBN), it appears ripe enough to reflect and take stock of achievements to date, having inherited a ramshackle financial system. It is not surprising, therefore, that the last Monetary Policy Committee (MPC) meeting provided a great opportunity for CBN Governor Olayemi Cardoso to reflect on the period from his assumption of office on September 22, 2023, to date.
According to Cardoso, “We were coming from a very bad place indeed. We were coming from a place where confidence had been lost in the bank and in the country, and that was manifested very clearly in the confidence that was lost in our currency.” He recounted that there was a time when the nation’s currency was regularly depreciating to the extent that businesses could not plan due to arbitrary changes in prices.
But undeterred by the circumstances he met on ground, Cardoso revealed that he set to work by assembling experts from diverse socioeconomic backgrounds. He acknowledged that such an assemblage of individuals from academia, research, international consulting, banking, and other fields was of immense help in steering the CBN to its present state of stability and progress after undergoing radical reforms. To him, the current state of the nation’s apex bank constitutes the proudest moment and achievement, because the bank had been taken back to its core mandates.
The CBN Governor recalled that in September 2023, the nation’s inflation rate of 26.7 per cent was triggered by the bank’s former management, which, through Ways and Means advances, had created over N22.7 trillion, thus plunging Nigeria into the situation citizens found themselves in. “If you recall, Ways and Means had got to N22.7 trillion. That fuelled the very sorry situation we had with inflation. We also had interventions of over N10 trillion. You’re pumping so much liquidity into a system with barely anything to show for it. And we all know what inflation is about: too much money chasing too few goods.
“So the result of that couldn’t have put us in a good place. Our responsibility was to restore stability, and the proudest moments have been in our ability, over the years, to take the right decisions that have brought us back there.
“In addition, recall the foreign exchange market. We had a very dysfunctional foreign exchange market, with a multiplicity of rates. The rate you got depended on who you knew and the access you had,” Cardoso added.
He revealed that his management team had succeeded in closing that gap by unifying exchange rates, because it was unfair that some people should profit at the expense of others; secondly, the losses from the differential exchange rates were far higher than the losses from the fuel subsidy. In his words: “The losses from the fuel subsidy were in the region of 2.2 per cent of GDP, that’s a staggering amount of money. But guess what? The losses we were making as a result of multiple exchange rate windows were even higher: 3 per cent of GDP. Between the two, that’s 5.2 per cent of GDP lost , not sustainable by any stretch of the imagination. We are pleased that we’ve been able to eliminate that distortion, and that our willing-buyer, willing-seller system, which allows transparency and lets the market find its own level, is where we are today.”
Another key milestone the CBN Governor mentioned was the recapitalisation of the banking sector after some 20 years, the first major policy announcement he made on assuming office. This was considered critical given the precarious condition of banks at the time and the objective of a $1 trillion economy. Within the years under review, the CBN has also rebuilt reserves, currently in excess of $55 billion, the highest in over 18 years.
At its 307th meeting, held on September 21–22, 2026, the MPC reviewed recent trends in the global and domestic economic environment, considered emerging risks to the outlook, and evaluated their implications for monetary policy. The meeting, attended by 11 members, resolved to: reset the Monetary Policy Rate (MPR) at 23 per cent; recalibrate the Standing Facilities Corridor to +50/-300 basis points around the MPR; and retain the Cash Reserve Requirement (CRR) for Deposit Money Banks at 45.00 per cent, Merchant Banks at 16.00 per cent, and non-TSA public sector deposits at 75.00 per cent.
Reasons
Reading the communiqué after the two-day session, the CBN Governor, who chairs the Committee, explained that the decision to reset the MPR and recalibrate the policy corridor was an important operational realignment aimed at strengthening monetary policy transmission and reinforcing the primacy of the MPR.
“The MPC emphasised that the recalibration of the corridor does not constitute a change in the current monetary policy stance, but rather an operational reset to enhance the effectiveness of monetary policy and support the transition to an inflation-targeting framework. Members are of the view that the current macroeconomic environment remains supportive of such a recalibration without undermining the disinflation process,” he stressed.
The MPC’s decisions have since been applauded by the Director-General of the Manufacturers Association of Nigeria (MAN), Segun Ajayi-Kadir, and the Vice-President of the Abuja Chamber of Commerce and Industry (ACCI), Chijioke Ekechukwu.
Considerations
In arriving at its decision, the Committee noted that the divergence between the MPR and prevailing market rates had weakened the effectiveness of monetary policy transmission. Members noted that the Bank’s ongoing repair of the monetary policy implementation framework, including the adoption of NOFR as a transaction-based operational benchmark, has improved the transparency of money market operations. The Committee therefore considered a reset of the MPR and recalibration of the corridor appropriate to better align the framework with market realities, strengthening policy transmission and restoring the MPR as the principal signal of monetary policy. Members emphasised that the recalibration is an operational realignment and should not, in itself, be construed as a change in the underlying policy stance.
The MPC broadly noted the increasing resilience of the Nigerian economy, reflected in moderating inflation, robust external reserve buffers, improved external sector fundamentals, and strengthening investor confidence. The Committee acknowledged the considerable improvement in the balance of payments surplus, which rose to $3.51 billion in Q2 2026, compared with $2.38 billion in Q1 2026. Similarly, the current account surplus increased by 67.92 per cent to $7.54 billion in Q2 2026, from $4.49 billion in Q1 2026.
The Committee particularly noted, with satisfaction, the progress of the disinflation process, evidenced by three consecutive months of decline in headline inflation despite lingering geopolitical tensions in the Middle East and the associated increase in global energy prices. Members observed that the moderation in inflation reflected the effectiveness of previous policy tightening measures, sustained exchange rate stability, and improved inflation expectations. The MPC also welcomed the Presidential Initiative on the National Affordable CNG Transit Programme, which is expected to lower transportation costs and support the continued decline in inflationary pressures.
The MPC further acknowledged the renewed commitment to policy coordination following the signing of a Memorandum of Understanding on fiscal-monetary coordination between the Federal Government of Nigeria (represented by the Federal Ministry of Finance) and the CBN. This development, among others, is expected to provide a structured framework for strengthening policy harmonisation towards achieving low and stable inflation.
Members noted the strengthening of the banking industry following the successful recapitalisation programme, which has enhanced banks’ capital buffers, resilience, and capacity to finance long-term projects in critical sectors of the economy.
In the Committee’s assessment, these positive macroeconomic developments, taken together, reaffirmed the appropriateness of the timing and created sufficient headroom for the reset of the policy rate corridor.
Price and Other Domestic Developments
Headline inflation (year-on-year) slowed to 15.39 per cent in August 2026, from 15.43 per cent in the preceding month, driven by both food and core measures. Food inflation declined to 19.57 per cent in August 2026 from 20.31 per cent in July 2026, largely reflecting moderation in the prices of palm oil, vegetables, and meat, among others. Core inflation similarly moderated to 13.29 per cent in August 2026 from 14.97 per cent in July 2026, driven by lower transport and healthcare costs. The 12-month moving average headline inflation rate continued its decline to 16.30 per cent in August 2026 from 16.89 per cent in July 2026, marking twenty consecutive months of moderation, an indication of sustained easing in underlying price pressures. On a month-on-month basis, headline inflation slowed to 0.71 per cent in August 2026 from 1.57 per cent, driven mainly by moderation in food inflation.
Real GDP grew by 4.43 per cent in the second quarter of 2026, up from 3.89 per cent in the preceding quarter, reflecting improved performance in both the non-oil and oil sectors. The non-oil sector expanded by 4.31 per cent, compared with 3.94 per cent in the first quarter of 2026, driven largely by increased activity in information and communications technology, crop production, real estate, livestock, financial services, and trade. Growth in the oil sector similarly accelerated to 7.31 per cent, compared with 2.57 per cent in the preceding quarter, supported by increased production and investment. The composite Purchasing Managers’ Index rose to 52.7 index points in August 2026 from 51.1 in July, suggesting further economic expansion.
Gross external reserves stood at $55.25 billion on September 18, 2026, the highest in 18 years, sufficient to finance approximately 11.3 months of imports of goods and services.
Global Developments
The global growth projection remains at 3.0 per cent for 2026, compared with 3.5 per cent in 2025, reflecting shocks from the Middle East conflict, persistent trade policy uncertainty, and constrained fiscal space. The slowdown is, however, expected to be partly offset by stronger technology-related investment. Growth prospects remain uneven, with energy-importing and low-income economies facing greater pressure from elevated energy costs and weaker fiscal buffers.
Risks to global inflation remain tilted to the upside, as persistent supply chain disruptions, elevated crude oil and other commodity prices, and increasing trade fragmentation could intensify price pressures. Combined with the possibility of renewed geopolitical tensions, these pressures could delay the normalisation of monetary policy.
Outlook
Domestic output growth is expected to remain resilient for the rest of 2026, supported by continued improvement in crude oil production, expansion in agriculture, and other business activities, as suggested by the Purchasing Managers’ Index.
Inflation is projected to moderate further in the short to medium term, underpinned by stability in the foreign exchange market, the lagged impact of earlier monetary policy tightening, and expectations of improved food supply as the harvest season progresses.
Overall, the outlook for the domestic economy remains positive, although prolonged geopolitical tensions in the Middle East and election-related spending could present upside risks to price development.
The Committee expressed its commitment to evaluating the effectiveness of the recalibrated interest rate corridor to ensure it supports the intended objective of strengthening policy transmission, and reaffirmed its resolve to keep future decisions data-dependent in sustaining disinflation.










 News3 days ago

 News1 week ago
 Business News7 days ago