…NIA pledges claims transparency, disciplined underwriting
By LOVETH-AZODO CHIJIOKE, Lagos
Following the landmark conclusion of the sector-wide recapitalisation exercise mandated by the Nigerian Insurance Industry Reform Act (NIIRA) 2025, the Commissioner for Insurance and Chief Executive of the National Insurance Commission (NAICOM), Mr. Olusegun Ayo Omosehin, has charged Nigerian underwriters to pivot from capital accumulation to real underwriting capacity, declaring that financial strength is meaningless if it fails to translate into prompt claims payment, public trust, and economic growth.
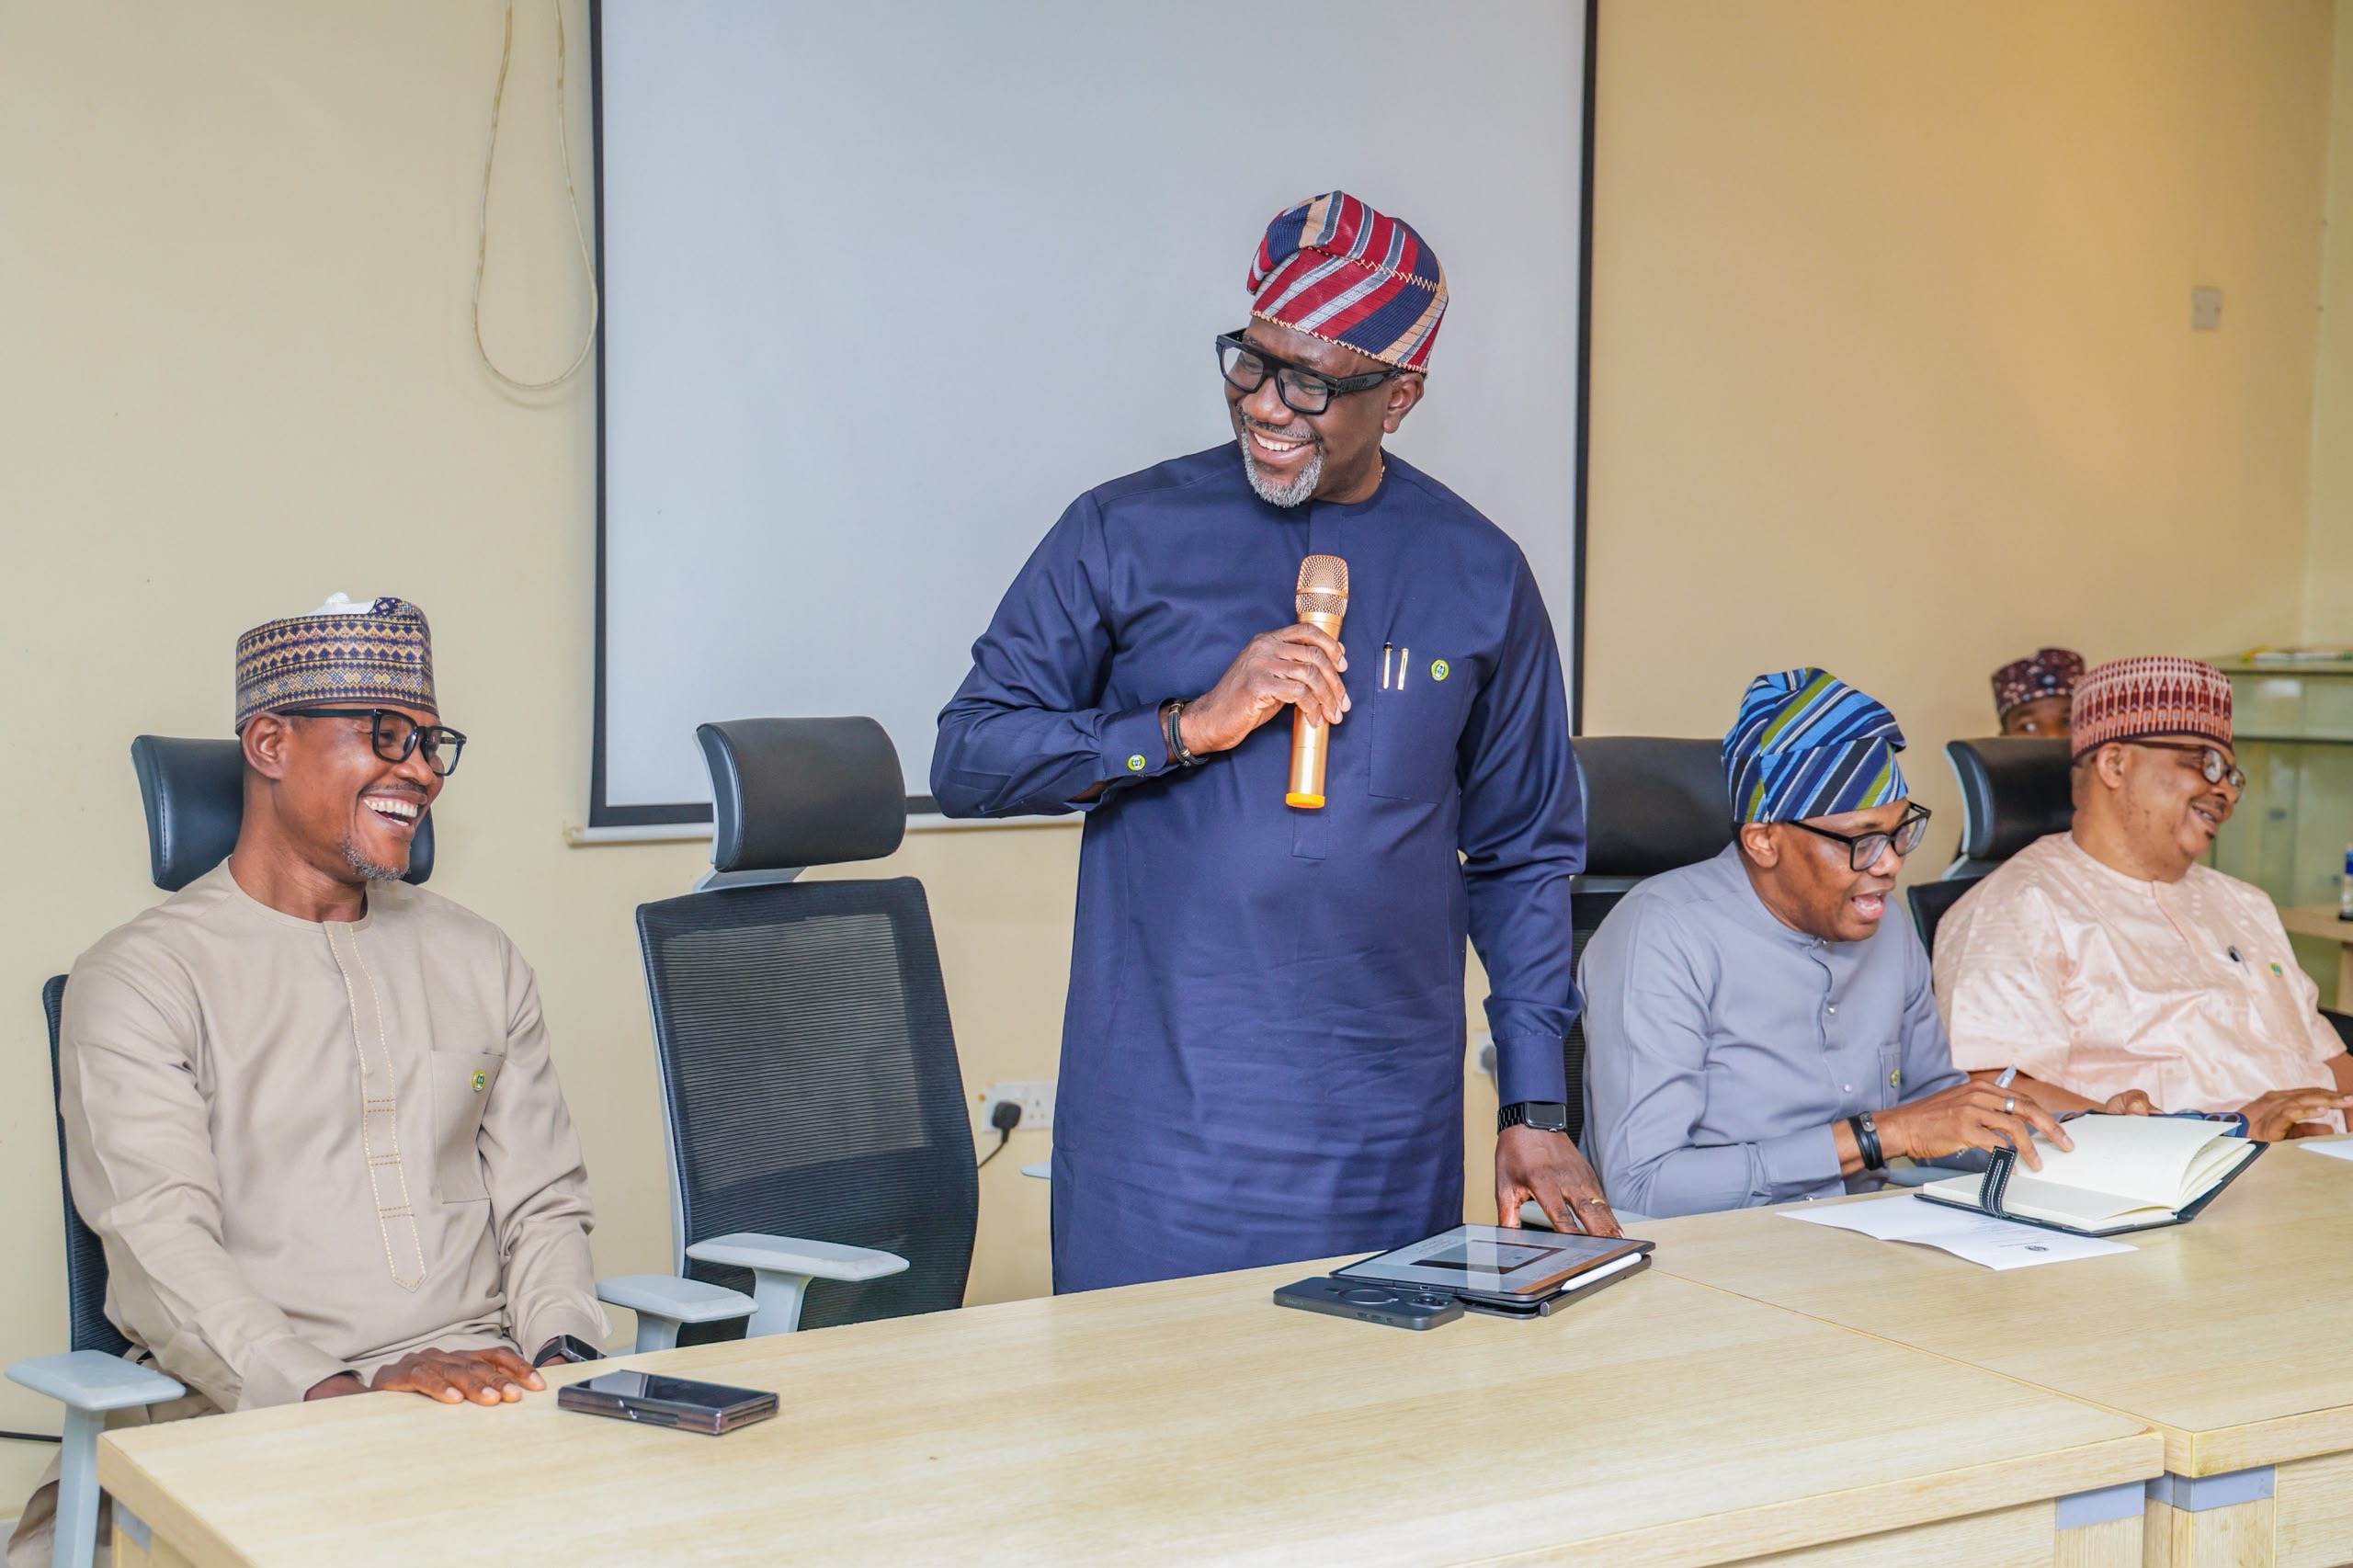
Omosehin gave this charge while delivering the keynote address at the BusinessDay Insurance Conference 2026, held Wednesday at the Victoria Island, Lagos.
Speaking on the theme, “From Capital to Capacity: Driving Growth, Innovation and Trust in Nigeria’s Insurance Sector,” the insurance commissioner stressed that the recapitalisation exercise was never conceived as an end in itself, warning that mere balance sheet expansion would not bridge Nigeria’s long-standing low insurance penetration gap.
“Capital without capacity is merely a number on a balance sheet,” Omosehin asserted before an audience of industry captains, foreign investors, and policymakers. “The era of measuring progress by capital alone is behind us. Capital becomes meaningful only when it translates into better service delivery, stronger governance, technological advancement, prompt claims settlement, product innovation, and improved customer experiences.”
He explained that while solvency remains critical for any institution built on promises, the central question facing boardrooms today is what the newly raised funds are accomplishing.
“Has it strengthened underwriting capacity? Has it enhanced claims-paying ability? Has it improved customer satisfaction? Has it increased public confidence? These are the questions that truly matter,” Omosehin said.
Reiterating that claims payment remains the single most visible proof of insurance value, the NAICOM boss stressed that every prompt, fair settlement reinforces trust, while every delay or unresolved grievance deepens cynicism.
Omosehin also underscored the human capital imperative, noting that sophisticated emerging exposures ranging from cyber threats, artificial intelligence risks, and climate volatility to complex supply chain disruptions require highly skilled professionals equipped with global competencies to domesticate risk retention.
Corroborating the regulator’s stance, the Chairman of the Nigerian Insurers Association (NIA), Mrs. Ebelechukwu Nwachukwu, disclosed that the recapitalisation exercise spurred by the NIIRA 2025 has yielded an aggregate capital base exceeding N1.079 trillion.
According to her, 50 insurance and reinsurance firms successfully met the commission’s stringent Minimum Capital Requirements (MCR), attracting both domestic and foreign direct investments into the market.
Nwachukwu commended NAICOM’s transparent verification procedures, noting that the legislative framework has established the legal and structural bedrock needed to elevate the sector to global best practices. She warned, however, that operators must shun complacency, advising that expanded capital buffers must be strictly anchored on underwriting discipline, adequate pricing, and aggressive technology adoption to reach unserved demographics in places like Kano, Aba, and Ibadan.
“The recapitalisation exercise has produced a sector with stronger, better-capitalised players capable of underwriting large infrastructure risks and an expanded compulsory insurance market,” Nwachukwu said. “The capital is in place; the legal framework is in place. The question before every boardroom now is: what do we do with it? Complacency now would be a betrayal of the opportunity that NIIRA has created.”
Pledging the NIA’s commitment to self-regulation and market integrity, Nwachukwu affirmed that the association would champion claims excellence, encourage full public disclosure of claims settlements, and build technical capacity in specialised segments such as energy, climate-related coverages, and agricultural insurance.









 Business News7 days ago
 Business News1 week ago