Connect with us

Business News

NAICOM Clamps Down on Board Abuse, Ties Capital Requirements to Underwriting Quality

Published

on

By LOVETH-AZODO CHIJIOKE, Lagos
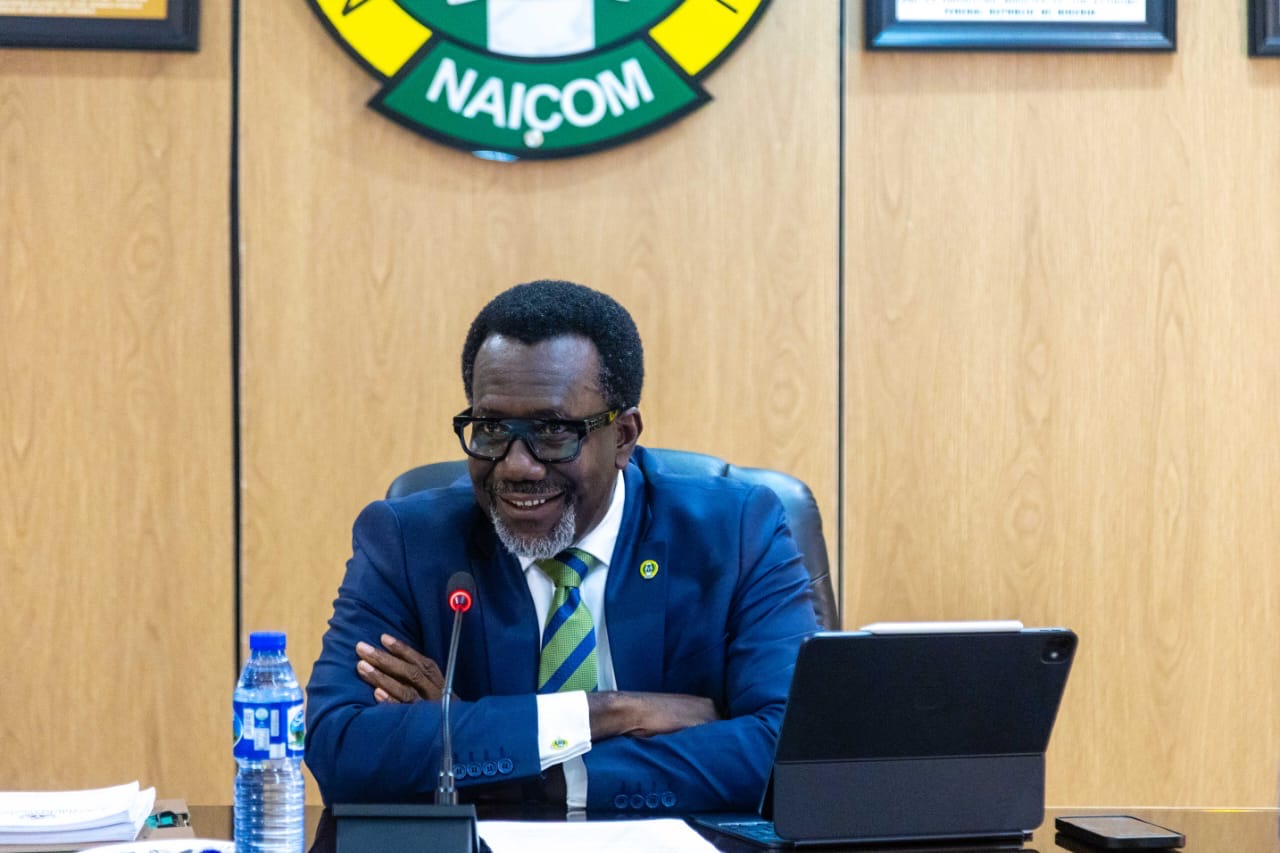
The National Insurance Commission (NAICOM) has escalated its regulatory enforcement against boardroom misconduct, warning insurance operators that underwriting recklessness, poor risk selection, and insider abuse will now automatically attract punitive capital surcharges.
Under the emerging Risk-Based Capital (RBC) supervisory framework established by the Nigerian Insurance Industry Reform Act (NIIRA) 2025, an underwriter’s capital adequacy is no longer treated as a static balance sheet figure. Instead, required capital will fluctuate dynamically based on the prudence or recklessness of underwriting and governance decisions made at the board level.
Speaking at the 8th Insurance Directors’ Conference in Lagos, the Special Adviser to the President on Economic Affairs, Dr. Tope Fasua, told board chairs and chief executives that capital efficiency in the post-recapitalisation market will be won or lost in boardroom committees.
According to Fasua, the era of treating statutory minimum capital as a one-time compliance ticket has ended. Under NIIRA 2025, which repealed and unified legacy statutes including the Insurance Act 2003 and the NAICOM Act 1997 insurers must maintain capital equal to the higher of the statutory floor or a risk-based figure computed directly by the regulator.
“Risk-based capital is not a fixed number; it moves with the insurer’s actual risk profile, which is set by the decisions its board and management make,” Fasua stated. “A board that underwrites poorly, prices badly, or under-reserves does not just damage profitability it directly raises the capital NAICOM will require the company to hold.”
To protect policyholder funds from insider expropriation, the legal framework introduces stringent curbs on credit exposures to board members. Under the provisions of NIIRA 2025, related-party lending to non-executive directors is strictly prohibited, with the statute prescribing a punitive financial sanction equal to double the borrowed amount for any violation.
The regulatory architecture also dilutes executive dominance in corporate boardrooms by capping executive directors at a maximum of 40 per cent of total board composition. To ensure objective oversight, underwriting firms are mandated to appoint at least two independent non-executive directors, who must hold the chairmanships of both the Audit and Compliance Committee and the Enterprise Risk Management and Governance Committee.
In addition, the framework establishes a strict separation of powers by barring board chairmen from serving on any board committees, thereby eliminating conflicts of interest and preserving the chair’s independent oversight role. To prevent anticompetitive practices and conflicting fiduciary loyalties, directors serving on the board of one licensed insurance firm are expressly prohibited from holding concurrent directorships across rival underwriting institutions.
Fasua reminded operators that NAICOM’s 2024 dissolution of the board and management of African Alliance Insurance Plc where an interim management team was installed following protracted solvency distress serves as an ongoing regulatory precedent of the state’s willingness to dismantle errant boards.
For policyholders and corporate clients, tying capital adequacy directly to underwriting discipline marks a significant structural safeguard against systemic insolvency and delayed claims. By penalizing reckless rate-cutting and mispriced risk books with higher mandatory solvency buffers, the commission aims to ensure that only well-governed, technically sound underwriters can underwrite high-exposure risks across key sectors of the economy.
Fasua noted that holding technical credentials, such as associateship of the Chartered Insurance Institute of Nigeria (ACIIN), or clearing regulatory cross-checks with the Central Bank of Nigeria (CBN), Securities and Exchange Commission (SEC), NDIC, and PenCom, merely constitutes a baseline requirement. Under the Companies and Allied Matters Act (CAMA) 2020, directors remain legally bound by an active duty of care, skill, and fiduciary independence, requiring them to challenge management on risky underwriting and reserving models before insolvency looms.

Advertisement
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

RENEWED HOPE AGENDA

NRS: MANAGE YOUR TAXES ONLINE

Our Naira Our Pride

NNPC: WE ARE HIRING

THE RENEWED HOPE AGENDA

ADVERTISEMENT

PRESS RELEASE

Click to read full text


CAVEAT EMPTOR

Advertisement

CBN Advert

Click the link to visit
Advertisement
Advertisement
Advertisement

Happy New Year

Facebook

Advertisement
Advertisement

Breaking News...